2026 Housing Market Outlook: Market Reset, Affordability and Policy Risk
As 2025 closed, the macro picture was less about collapse or acceleration and more about tension between solid economic mechanics and growing pockets of stress.
Growth is solid while labor cools
Growth data remains mechanically strong, helped by trade dynamics and resilient consumption. Labor is clearly cooling at the margin. Unemployment is drifting higher, job growth is uneven, and revisions are likely to soften prior strength. That combination keeps the economy expanding while reducing the Fed's margin for error.
Inflation is a measurement problem
Inflation is the most debated signal, and increasingly a measurement problem rather than a directional one. Headline and core readings are near the Fed's comfort zone, but shelter inflation continues to overstate real-world rent dynamics. Correcting for that distortion would place inflation closer to equilibrium than fear-driven narratives suggest.
That supports a slow normalization path rather than renewed tightening. It does not guarantee aggressive easing.
The housing reset is creating operator-level opportunity
Market structure reset
The number of intermediaries fell sharply, and easy-money behavior largely exited.
| Group | Change |
|---|---|
| Wholesalers | About 80,000 down to about 10,000 (-82%) |
| Mortgage brokers | -60% |
| Active agents | -50% or more |
Seller behavior is shifting too: price cuts, seller financing, credits and rate buydowns. Buyer leverage is rising in most markets, with the Northeast still tighter.
Housing demand and affordability
Affordability is improving quietly.
| Signal | Latest |
|---|---|
| Average monthly payment | $2,665 (down from $3,000+) |
| Mortgage demand | +28% week over week |
| Purchase applications | +16% week over week, +13% year over year |
| Refinance applications | +40% week over week, +128% year over year |
| Adjustable-rate mortgage share | About 10% (versus 3% to 4% prior) |
| Homes owned mortgage-free | 40%+ |
| Housing starts | Lowest since May 2020 |
Macro and policy signals shaping 2026
| Metric | Status |
|---|---|
| CPI | 2.7% headline, 2.6% core |
| Real-time inflation | Under 2% |
| Unemployment | About 4.4% to 4.7% |
- Fed outlook: cuts likely later in 2026.
- Mortgage rates: about 6.0% to 6.2%, and volatile.
- Inventory growth: West +14%, South +12%, Midwest +11%.
Investor takeaway
This is a healthier market structure: fewer speculators, real buyer demand, and flexible sellers.
For how these signals played out locally, see Cincinnati real estate in 2026.
Originally published in the Cincy Cash Flow Report on January 28, 2026.
Keep reading
Cincinnati Real Estate in 2026: Strong Demand, Tighter Execution
Cincinnati demand across housing, infrastructure and capital programs is intact. Power access, approvals and governance now decide who gets deals done.
3 min readRead →
Cincinnati Market Update, April 2026: Building Boom and Higher-for-Longer Rates
A GE Aerospace commitment, the highest multifamily construction quarter in two years and a Fed on hold. What March meant for Cincinnati investors.
3 min readRead →
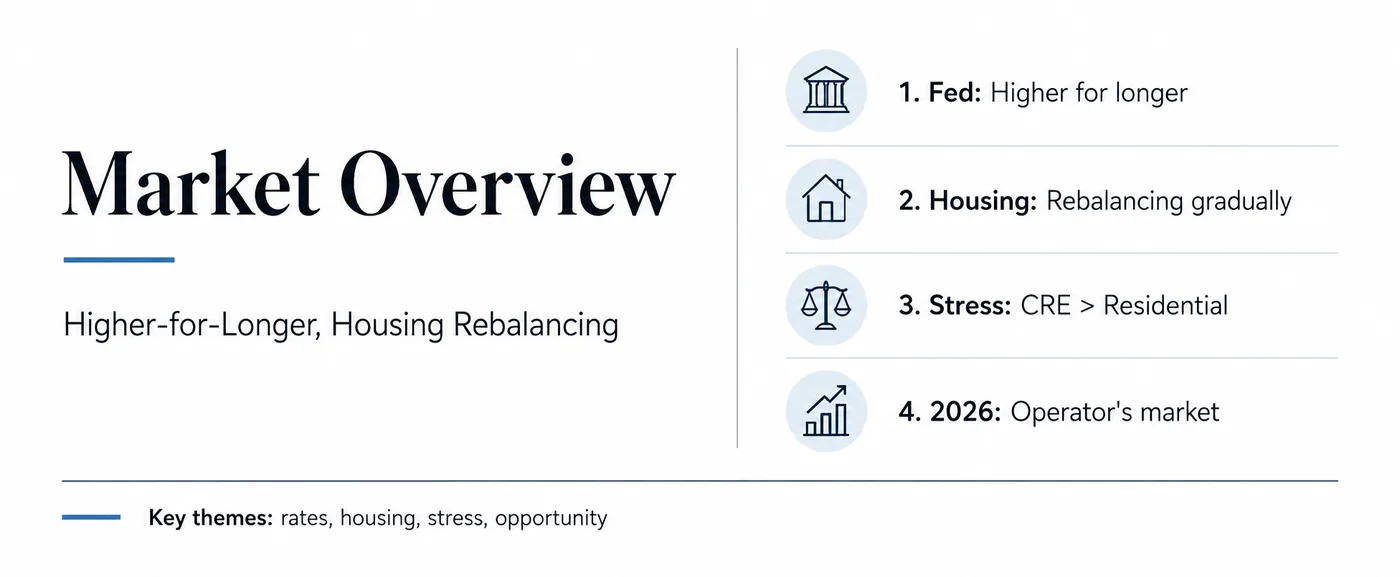
Higher for Longer: The Fed, Housing and Where Distress Is Showing Up
Rate relief is a possibility, not a plan. Where housing is rebalancing, where commercial real estate losses are realizing, and how operators should position.
2 min readRead →