Multifamily Insurance Costs: How to Underwrite Around Rising Premiums
Insurance has quietly become one of the fastest growing expense lines in multifamily, and many operators are still underestimating it.
Why premiums keep climbing
Over the past 12 to 24 months, per door premiums have jumped due to higher catastrophe losses, reinsurance repricing, and rising replacement costs. Carriers are also tightening terms, raising deductibles, and pulling capacity from older or heavier value-add assets.
The underwriting lag
The issue is lag. Many operators still budget insurance off pre-2022 numbers or early broker indications. The increase becomes real at renewal, when premiums reset higher and lenders true up escrows.
That gap flows straight through NOI, compresses DSCR, and can delay refinances and reduce cash flow.
| Units | Miss per unit | Lost NOI |
|---|---|---|
| 100 | $300 | $30,000 |
How to underwrite around it
- Use trailing 12 actual premiums, not pro forma estimates.
- Stress test renewals 25% to 50% higher, especially in secondary markets.
- Quote early with a multifamily-focused insurance broker.
- Model deductibles and add an insurance reserve buffer.
Insurance also comes up in conversations with brokers who have moved to the ownership side. Read what a Cincinnati multifamily broker learned as an owner for a real-world example.
Originally published in the Cincy Cash Flow Report on January 28, 2026.
Keep reading
2026 Housing Market Outlook: Market Reset, Affordability and Policy Risk
Solid growth, cooling labor, distorted shelter inflation and a healthier market structure. The macro signals shaping the 2026 housing market for investors.
2 min readRead →
Cincinnati Multifamily From the Broker Side: Lessons From JD Schmerge
A broker turned owner-operator on insurance, property taxes, C-class vacancy and the 10% renovation rule. Highlights from the Cincy REI Show.
2 min readRead →
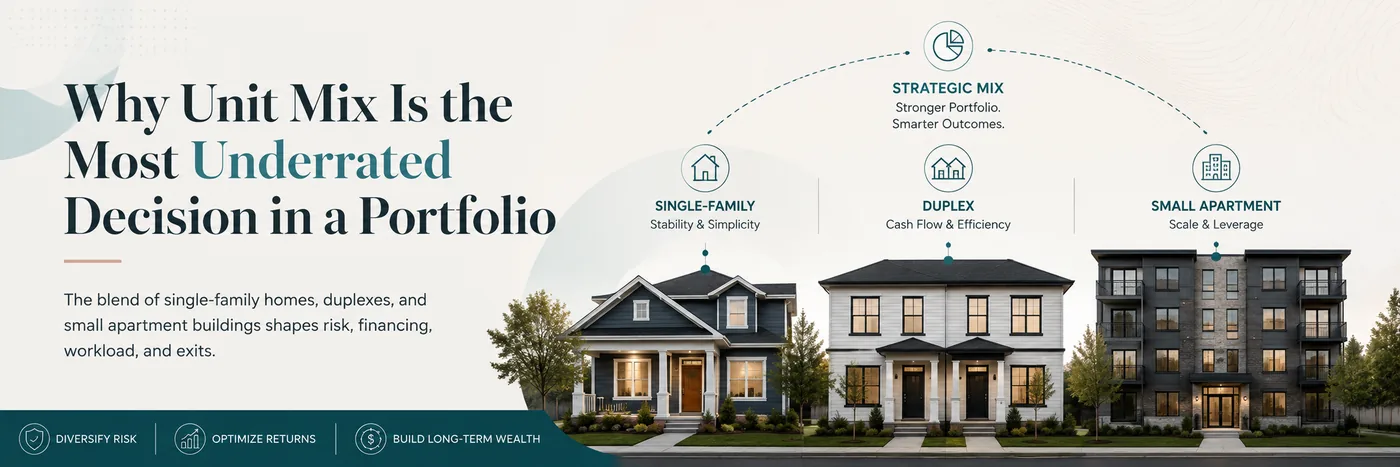
Unit Mix: The Most Underrated Decision in a Rental Portfolio
Single-family homes, duplexes and small apartments each do a different job. How unit mix sets your risk, financing, workload and exit.
3 min readRead →